GRAND PRAIRIE
Local $465 /month
$5,575 per year
Estimated average, $300,000 dwelling coverage
Why Pay More?

Single-Family Home

Townhome

Condo (HO-6)

Mobile / Manufactured Home

Other
Homeowners in Grand Prairie pay an average of $5,575 per year for a policy with $300,000 in dwelling coverage, or roughly $465 a month. Located between Dallas and Fort Worth, the city faces frequent spring hail and severe thunderstorms, which raise claim costs and push premiums higher for local homeowners.
The Texas average for homeowners insurance is about $4,668 a year, which places Grand Prairie roughly 19% higher than the statewide figure. Rising construction and labor costs across the Dallas–Fort Worth area increase the price of repairs, while repeated hail seasons lead many insurers to adjust rates and deductibles upward.
Nationally, homeowners pay an average of $2,808 a year, so Grand Prairie residents spend nearly double, or about 99% more, than the U.S. benchmark. Texas homeowners as a whole pay about 66% more than the national rate, largely because of its combined exposure to hail, severe wind, and coastal hurricanes.
GRAND PRAIRIE
Local$5,575 per year
Estimated average, $300,000 dwelling coverage
TEXAS
Statewide$4,668 per year
Estimated average, $300,000 dwelling coverage
USA
National$2,808 per year
Estimated average, $300,000 dwelling coverage

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.
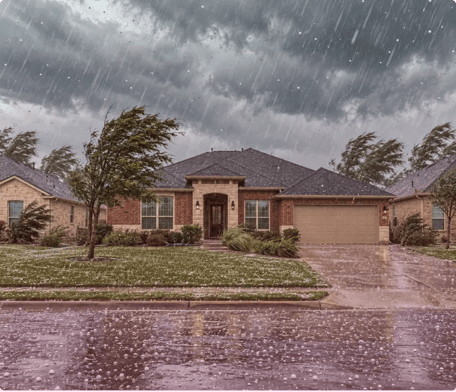
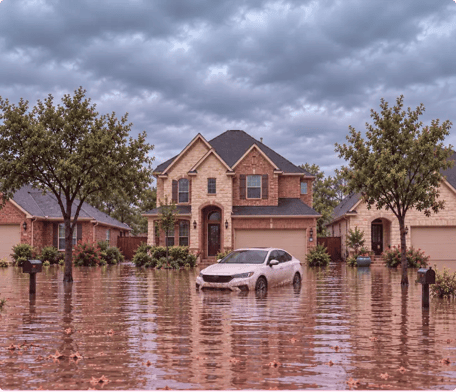
Home insurance rates in Grand Prairie are rarely the same from one household to the next. Each premium reflects a mix of personal details and property characteristics, so two neighbors with similar homes can receive very different quotes. Rates can also shift at renewal, sometimes without an obvious reason, which makes yearly budgeting harder for many families. When premiums change unexpectedly, homeowners may end up overpaying or reducing coverage to stay affordable. Reviewing your policy each year and comparing quotes helps you understand where your rate stands and why.

Home Age and Construction

Roof Age and Material

Distance From the Coast

Home Insurance Claims History

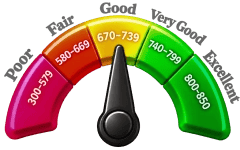
Credit-Based Insurance Score

Dwelling Value and Coverage Limit

Deductible Amount

Home Security and Safety Features

Neighborhood Crime Rate

Foundation or Water Damage Claims

Distance to Fire and Water Services
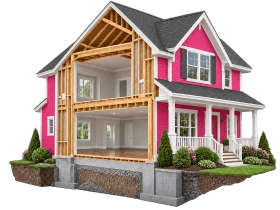
Premiums for homeowners insurance in Texas have climbed steadily, and Grand Prairie households feel that pressure when planning their yearly budgets. Discounts offer a practical way to lower costs without giving up the coverage your home needs. Even a few small credits can add up to meaningful savings over the life of a policy, making it easier to set aside funds for repairs, deductibles, or other expenses. Asking about every available discount is worth the effort. Below is a list of discounts you can avail of when applying for homeowners insurance:

Multi-Policy Discount

Claims-Free Discount

New or Renovated Roof Discount

Monitored Alarm System Discount

Protective Device Discount

Gated Community or HOA Discount

New Home Discount

First-Time Homebuyer Discount

Non-Smoker Discount

Loyalty Discount

Automatic Payment Discount

Paid-in-full Discount

Senior Citizen Discount

Group Discount

Early Renewal Discount
CINCO has insured Texas homeowners since 1981 and now holds more than 7,000 five-star Google reviews. Our licensed agents build long-term relationships with Grand Prairie clients and review coverage at every renewal, so policies keep pace with rising rebuilding costs, roof replacements, home additions, and other changes in the household.
Agents also explain new policy options and the discounts clients qualify for, such as bundling home and auto or installing an impact-resistant roof. Our bilingual team serves Grand Prairie homeowners in both English and Spanish, from the first quote through claims, renewals, and any coverage questions that arise in between.
Single-Family Home
Townhome
Condo (HO-6)
Mobile / Manufactured Home
Other
Tell us! what you want?
Pick the best coverage that fits you!
Get Your Insurance!
With over 7,000+ 5 Star Google reviews and counting - we deliver what matters
Chris Daniels
Crystal has shown the epitome of professionalism. She has exceptional poise and ability. She is truly an asset to this company and the insurance industry. I look forward to future deals with her.
Johnny Reighard
Edward was excellent. He was very friendly and highly knowledgeable, with an easygoing attitude and a down-to-earth personality. He helped us get a fantastic rate.
Lloyd
This was a great experience. I enjoyed talking with Amanda. She was very nice, had great energy, and created a good atmosphere. We need more people like her. Thank you, Cinco!
Kevin Hernandez
I had a really good experience with Edith. She made everything super easy, explained everything clearly, and helped me get a really good rate. I definitely recommend her.
Marcos Guido
Sandy is awesome. She will help you as much as she can. She provided great customer service and was willing to go above and beyond to get me the best rate possible.
Cliffton Boykin
Thank you to Julio Leija for assisting me with getting back on track with my coverage. He was polite and patient throughout the process. He helped me find the best insurance rate today!
Rick Ciesielski
Maresa was very helpful with my auto insurance coverage. She clearly explained how I could pay my monthly premium online so I could keep my coverage from expiring.
Kellye Carothers
Giselle was great at helping me get an insurance quote. She was very polite and helped me a lot. I will be meeting with her tomorrow to get my insurance. I hope you keep her—she’s really sweet.
Joss M
I recommend coming here. I went to different insurance places to get quotes, but I had to come back to Cinco Insurance. Monica was a great help and provided the best quotes.
Tashara
Denice was awesome in helping me find insurance for my car. I highly recommend her to anyone looking for insurance. She was able to find the lowest premium possible for me.
Brandon Reyes
I’d like to thank Karina for helping me out today. She had a very pleasant voice and set everything up for me in a timely manner. I hope she has a blessed day!
Edward Medina
Great service! Veronica was very understanding, took great care of me as a customer, and was very professional. Highly recommended for anyone looking for insurance.
Arturo Rodriguez
I was looking for insurance during a very crucial moment, and this is where I found my solution. Thank you for the great service, especially Ms. Amanda. I truly appreciate your help.
Maria Martinez
Cinco Insurance is awesome. They always answer my questions and are very professional. They always answer incoming calls and return calls in a timely manner. Julio, thank you for helping me.
Abby Frausto
Five stars for Edith! She made the process super easy. Her customer service and communication skills were amazing. Thank you so much, Cinco Insurance!
Chris Daniels
Crystal has shown the epitome of professionalism. She has exceptional poise and ability. She is truly an asset to this company and the insurance industry. I look forward to future deals with her.
Johnny Reighard
Edward was excellent. He was very friendly and highly knowledgeable, with an easygoing attitude and a down-to-earth personality. He helped us get a fantastic rate.
Lloyd
This was a great experience. I enjoyed talking with Amanda. She was very nice, had great energy, and created a good atmosphere. We need more people like her. Thank you, Cinco!
Kevin Hernandez
I had a really good experience with Edith. She made everything super easy, explained everything clearly, and helped me get a really good rate. I definitely recommend her.
Marcos Guido
Sandy is awesome. She will help you as much as she can. She provided great customer service and was willing to go above and beyond to get me the best rate possible.
Cliffton Boykin
Thank you to Julio Leija for assisting me with getting back on track with my coverage. He was polite and patient throughout the process. He helped me find the best insurance rate today!
Rick Ciesielski
Maresa was very helpful with my auto insurance coverage. She clearly explained how I could pay my monthly premium online so I could keep my coverage from expiring.
Kellye Carothers
Giselle was great at helping me get an insurance quote. She was very polite and helped me a lot. I will be meeting with her tomorrow to get my insurance. I hope you keep her—she’s really sweet.
Joss M
I recommend coming here. I went to different insurance places to get quotes, but I had to come back to Cinco Insurance. Monica was a great help and provided the best quotes.
Tashara
Denice was awesome in helping me find insurance for my car. I highly recommend her to anyone looking for insurance. She was able to find the lowest premium possible for me.
Brandon Reyes
I’d like to thank Karina for helping me out today. She had a very pleasant voice and set everything up for me in a timely manner. I hope she has a blessed day!
Edward Medina
Great service! Veronica was very understanding, took great care of me as a customer, and was very professional. Highly recommended for anyone looking for insurance.
Arturo Rodriguez
I was looking for insurance during a very crucial moment, and this is where I found my solution. Thank you for the great service, especially Ms. Amanda. I truly appreciate your help.
Maria Martinez
Cinco Insurance is awesome. They always answer my questions and are very professional. They always answer incoming calls and return calls in a timely manner. Julio, thank you for helping me.
Abby Frausto
Five stars for Edith! She made the process super easy. Her customer service and communication skills were amazing. Thank you so much, Cinco Insurance!
Chris Daniels
Crystal has shown the epitome of professionalism. She has exceptional poise and ability. She is truly an asset to this company and the insurance industry. I look forward to future deals with her.
Johnny Reighard
Edward was excellent. He was very friendly and highly knowledgeable, with an easygoing attitude and a down-to-earth personality. He helped us get a fantastic rate.
Lloyd
This was a great experience. I enjoyed talking with Amanda. She was very nice, had great energy, and created a good atmosphere. We need more people like her. Thank you, Cinco!
Kevin Hernandez
I had a really good experience with Edith. She made everything super easy, explained everything clearly, and helped me get a really good rate. I definitely recommend her.
Marcos Guido
Sandy is awesome. She will help you as much as she can. She provided great customer service and was willing to go above and beyond to get me the best rate possible.
Cliffton Boykin
Thank you to Julio Leija for assisting me with getting back on track with my coverage. He was polite and patient throughout the process. He helped me find the best insurance rate today!
Rick Ciesielski
Maresa was very helpful with my auto insurance coverage. She clearly explained how I could pay my monthly premium online so I could keep my coverage from expiring.
Kellye Carothers
Giselle was great at helping me get an insurance quote. She was very polite and helped me a lot. I will be meeting with her tomorrow to get my insurance. I hope you keep her—she’s really sweet.
Joss M
I recommend coming here. I went to different insurance places to get quotes, but I had to come back to Cinco Insurance. Monica was a great help and provided the best quotes.
Tashara
Denice was awesome in helping me find insurance for my car. I highly recommend her to anyone looking for insurance. She was able to find the lowest premium possible for me.
Brandon Reyes
I’d like to thank Karina for helping me out today. She had a very pleasant voice and set everything up for me in a timely manner. I hope she has a blessed day!
Edward Medina
Great service! Veronica was very understanding, took great care of me as a customer, and was very professional. Highly recommended for anyone looking for insurance.
Arturo Rodriguez
I was looking for insurance during a very crucial moment, and this is where I found my solution. Thank you for the great service, especially Ms. Amanda. I truly appreciate your help.
Maria Martinez
Cinco Insurance is awesome. They always answer my questions and are very professional. They always answer incoming calls and return calls in a timely manner. Julio, thank you for helping me.
Abby Frausto
Five stars for Edith! She made the process super easy. Her customer service and communication skills were amazing. Thank you so much, Cinco Insurance!
Have questions or need assistance? Our team is here to help — reach out to us using the form below, and we'll get back to you as soon as possible.
CALL US:
855-336-8555TEXT US:
855-336-8555EMAIL:
STARTSAVING@CINCOAUTOINSURANCE.COMVISIT US:
TO OUR NEAREST OFFICE