LUBBOCK
Local $224 /month
$2,690 per year
Estimated average, $300,000 dwelling coverage
Why Pay More?

Single-Family Home

Townhome

Condo (HO-6)

Mobile / Manufactured Home

Other
Homeowners in Lubbock pay an average of about $2,690 per year for homeowners insurance on a $300,000 dwelling policy with a $1,000 deductible, or roughly $224 a month. Hail, wind, and tornado claims shape local pricing, and older roofs or homes near low-lying drainage areas often pay more for coverage.
The Texas average is about $4,668 per year, putting Lubbock about 42% below the state average. Coastal hurricane exposure drives statewide rates higher, while Lubbock costs come mainly from storms in West Texas. Many carriers request roof photos or inspections, and separate wind and hail deductibles are more common locally.
Across the United States, homeowners pay an average of $2,808 a year, so Lubbock residents spend about 4% less than the national rate. Texas as a whole runs about 66% higher than that benchmark. Raising your deductible, upgrading to an impact-resistant roof, and comparing carriers can help keep premiums competitive.
LUBBOCK
Local$2,690 per year
Estimated average, $300,000 dwelling coverage
TEXAS
Statewide$4,668 per year
Estimated average, $300,000 dwelling coverage
USA
National$2,808 per year
Estimated average, $300,000 dwelling coverage

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.

Policy tip: Ask how roof age affects a wind or hail claim.
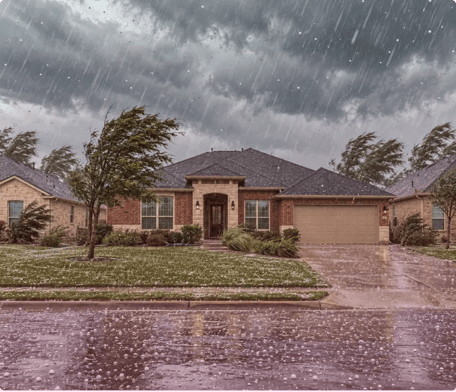
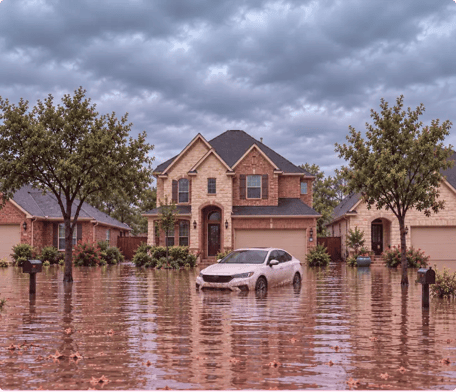
No two Lubbock homeowners pay exactly the same premium. Insurers start with personal details such as past claims, credit history, and deductible choice, then look at the home itself, including its age, roof, construction type, and replacement cost. Location adds another layer, since storm exposure and property theft rates vary from one Lubbock neighborhood to the next. Knowing which of these factors apply to you makes it easier to compare quotes and find practical ways to lower your annual rate over time.

Home Age and Construction

Roof Age and Material

Distance From the Coast

Home Insurance Claims History

Credit-Based Insurance Score

Dwelling Value and Coverage Limit

Deductible Amount

Home Security and Safety Features

Neighborhood Crime Rate

Foundation or Water Damage Claims

Distance to Fire and Water Services
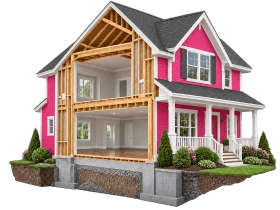
Discounts can lower coverage costs for Lubbock homeowners. Many insurers offer discounts for Class 4 impact-resistant roofs, which withstand hail better. Monitored alarms, updated wiring, and newer plumbing can also reduce your rate. A claims-free history helps too. Bundling home and auto with one carrier often brings extra savings. New homeowners should ask about discounts before closing and share any recent roof or safety upgrades. These simple steps make affordable homeowners insurance easier to find without cutting important coverage.

Multi-Policy Discount

Claims-Free Discount

New or Renovated Roof Discount

Monitored Alarm System Discount

Protective Device Discount

Gated Community or HOA Discount

New Home Discount

First-Time Homebuyer Discount

Non-Smoker Discount

Loyalty Discount

Automatic Payment Discount

Paid-in-full Discount

Senior Citizen Discount

Group Discount

Early Renewal Discount
Serving Texas since 1981, CINCO has built a strong record with homeowners statewide, supported by more than 7,000 five-star Google reviews. Our licensed agents understand how hail, high winds, and severe freezes affect Lubbock properties year-round and assist each client in selecting appropriate coverage limits and deductibles for their home.
CINCO provides a prompt, efficient quoting process for Lubbock homeowners. Agents can often prepare a quote within a single consultation and remain available for policy updates and claim assistance. In addition to homeowners coverage, CINCO offers auto, flood, and renters insurance, allowing clients to manage multiple policies through one agency.
Single-Family Home
Townhome
Condo (HO-6)
Mobile / Manufactured Home
Other
Tell us! what you want?
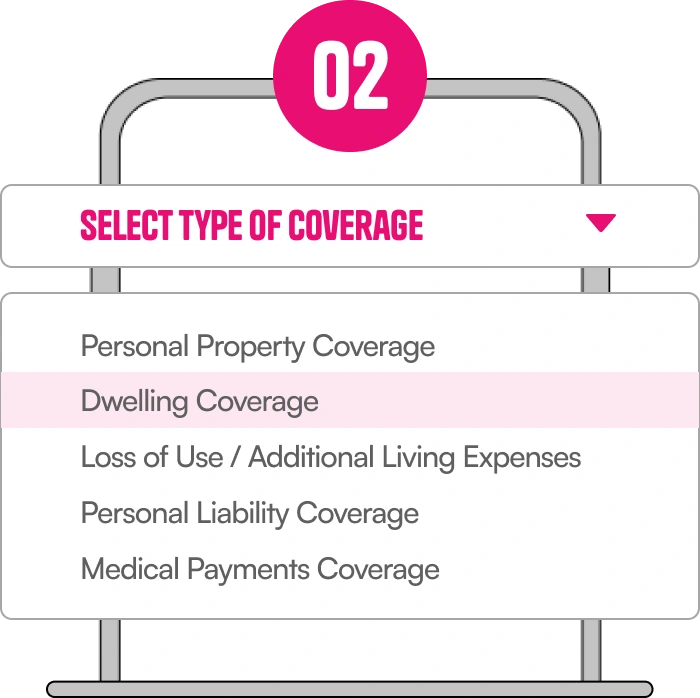
Pick the best coverage that fits you!
Get Your Insurance!
With over 7,000+ 5 Star Google reviews and counting - we deliver what matters
Chris Daniels
Crystal has shown the epitome of professionalism. She has exceptional poise and ability. She is truly an asset to this company and the insurance industry. I look forward to future deals with her.
Johnny Reighard
Edward was excellent. He was very friendly and highly knowledgeable, with an easygoing attitude and a down-to-earth personality. He helped us get a fantastic rate.
Lloyd
This was a great experience. I enjoyed talking with Amanda. She was very nice, had great energy, and created a good atmosphere. We need more people like her. Thank you, Cinco!
Kevin Hernandez
I had a really good experience with Edith. She made everything super easy, explained everything clearly, and helped me get a really good rate. I definitely recommend her.
Marcos Guido
Sandy is awesome. She will help you as much as she can. She provided great customer service and was willing to go above and beyond to get me the best rate possible.
Cliffton Boykin
Thank you to Julio Leija for assisting me with getting back on track with my coverage. He was polite and patient throughout the process. He helped me find the best insurance rate today!
Rick Ciesielski
Maresa was very helpful with my auto insurance coverage. She clearly explained how I could pay my monthly premium online so I could keep my coverage from expiring.
Kellye Carothers
Giselle was great at helping me get an insurance quote. She was very polite and helped me a lot. I will be meeting with her tomorrow to get my insurance. I hope you keep her—she’s really sweet.
Joss M
I recommend coming here. I went to different insurance places to get quotes, but I had to come back to Cinco Insurance. Monica was a great help and provided the best quotes.
Tashara
Denice was awesome in helping me find insurance for my car. I highly recommend her to anyone looking for insurance. She was able to find the lowest premium possible for me.
Brandon Reyes
I’d like to thank Karina for helping me out today. She had a very pleasant voice and set everything up for me in a timely manner. I hope she has a blessed day!
Edward Medina
Great service! Veronica was very understanding, took great care of me as a customer, and was very professional. Highly recommended for anyone looking for insurance.
Arturo Rodriguez
I was looking for insurance during a very crucial moment, and this is where I found my solution. Thank you for the great service, especially Ms. Amanda. I truly appreciate your help.
Maria Martinez
Cinco Insurance is awesome. They always answer my questions and are very professional. They always answer incoming calls and return calls in a timely manner. Julio, thank you for helping me.
Abby Frausto
Five stars for Edith! She made the process super easy. Her customer service and communication skills were amazing. Thank you so much, Cinco Insurance!
Chris Daniels
Crystal has shown the epitome of professionalism. She has exceptional poise and ability. She is truly an asset to this company and the insurance industry. I look forward to future deals with her.
Johnny Reighard
Edward was excellent. He was very friendly and highly knowledgeable, with an easygoing attitude and a down-to-earth personality. He helped us get a fantastic rate.
Lloyd
This was a great experience. I enjoyed talking with Amanda. She was very nice, had great energy, and created a good atmosphere. We need more people like her. Thank you, Cinco!
Kevin Hernandez
I had a really good experience with Edith. She made everything super easy, explained everything clearly, and helped me get a really good rate. I definitely recommend her.
Marcos Guido
Sandy is awesome. She will help you as much as she can. She provided great customer service and was willing to go above and beyond to get me the best rate possible.
Cliffton Boykin
Thank you to Julio Leija for assisting me with getting back on track with my coverage. He was polite and patient throughout the process. He helped me find the best insurance rate today!
Rick Ciesielski
Maresa was very helpful with my auto insurance coverage. She clearly explained how I could pay my monthly premium online so I could keep my coverage from expiring.
Kellye Carothers
Giselle was great at helping me get an insurance quote. She was very polite and helped me a lot. I will be meeting with her tomorrow to get my insurance. I hope you keep her—she’s really sweet.
Joss M
I recommend coming here. I went to different insurance places to get quotes, but I had to come back to Cinco Insurance. Monica was a great help and provided the best quotes.
Tashara
Denice was awesome in helping me find insurance for my car. I highly recommend her to anyone looking for insurance. She was able to find the lowest premium possible for me.
Brandon Reyes
I’d like to thank Karina for helping me out today. She had a very pleasant voice and set everything up for me in a timely manner. I hope she has a blessed day!
Edward Medina
Great service! Veronica was very understanding, took great care of me as a customer, and was very professional. Highly recommended for anyone looking for insurance.
Arturo Rodriguez
I was looking for insurance during a very crucial moment, and this is where I found my solution. Thank you for the great service, especially Ms. Amanda. I truly appreciate your help.
Maria Martinez
Cinco Insurance is awesome. They always answer my questions and are very professional. They always answer incoming calls and return calls in a timely manner. Julio, thank you for helping me.
Abby Frausto
Five stars for Edith! She made the process super easy. Her customer service and communication skills were amazing. Thank you so much, Cinco Insurance!
Chris Daniels
Crystal has shown the epitome of professionalism. She has exceptional poise and ability. She is truly an asset to this company and the insurance industry. I look forward to future deals with her.
Johnny Reighard
Edward was excellent. He was very friendly and highly knowledgeable, with an easygoing attitude and a down-to-earth personality. He helped us get a fantastic rate.
Lloyd
This was a great experience. I enjoyed talking with Amanda. She was very nice, had great energy, and created a good atmosphere. We need more people like her. Thank you, Cinco!
Kevin Hernandez
I had a really good experience with Edith. She made everything super easy, explained everything clearly, and helped me get a really good rate. I definitely recommend her.
Marcos Guido
Sandy is awesome. She will help you as much as she can. She provided great customer service and was willing to go above and beyond to get me the best rate possible.
Cliffton Boykin
Thank you to Julio Leija for assisting me with getting back on track with my coverage. He was polite and patient throughout the process. He helped me find the best insurance rate today!
Rick Ciesielski
Maresa was very helpful with my auto insurance coverage. She clearly explained how I could pay my monthly premium online so I could keep my coverage from expiring.
Kellye Carothers
Giselle was great at helping me get an insurance quote. She was very polite and helped me a lot. I will be meeting with her tomorrow to get my insurance. I hope you keep her—she’s really sweet.
Joss M
I recommend coming here. I went to different insurance places to get quotes, but I had to come back to Cinco Insurance. Monica was a great help and provided the best quotes.
Tashara
Denice was awesome in helping me find insurance for my car. I highly recommend her to anyone looking for insurance. She was able to find the lowest premium possible for me.
Brandon Reyes
I’d like to thank Karina for helping me out today. She had a very pleasant voice and set everything up for me in a timely manner. I hope she has a blessed day!
Edward Medina
Great service! Veronica was very understanding, took great care of me as a customer, and was very professional. Highly recommended for anyone looking for insurance.
Arturo Rodriguez
I was looking for insurance during a very crucial moment, and this is where I found my solution. Thank you for the great service, especially Ms. Amanda. I truly appreciate your help.
Maria Martinez
Cinco Insurance is awesome. They always answer my questions and are very professional. They always answer incoming calls and return calls in a timely manner. Julio, thank you for helping me.
Abby Frausto
Five stars for Edith! She made the process super easy. Her customer service and communication skills were amazing. Thank you so much, Cinco Insurance!
Have questions or need assistance? Our team is here to help — reach out to us using the form below, and we'll get back to you as soon as possible.
CALL US:
855-336-8555TEXT US:
855-336-8555EMAIL:
STARTSAVING@CINCOAUTOINSURANCE.COMVISIT US:
TO OUR NEAREST OFFICE